Opportunity Guide · Opportunity Guide · Financing
What an SBA Lender Looks for in a First-Time Owner
SBA-backed loans are one of the most common ways to fund a franchise or business purchase. Here is how lenders size you up, and how to prepare.
By The Opportunity Mag Editors7 min read
How SBA loans actually work
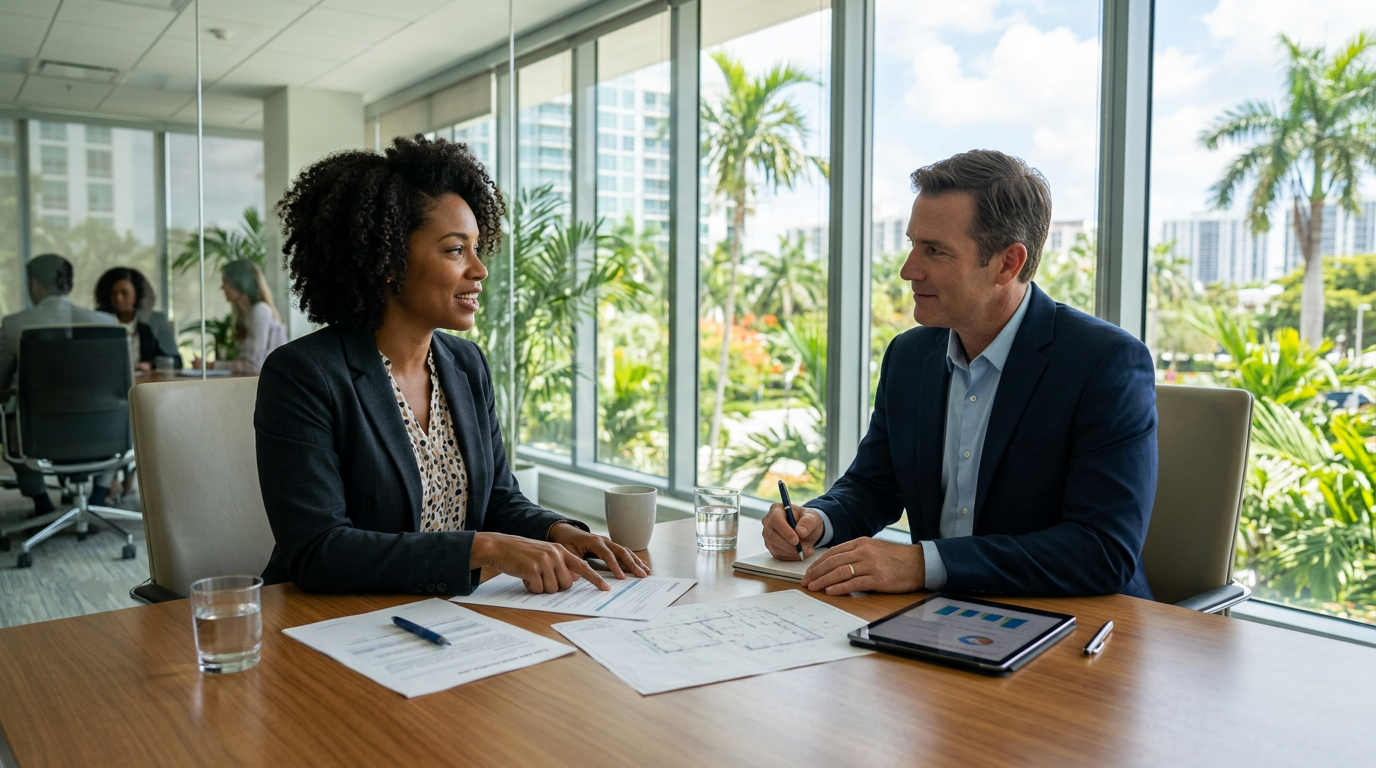
The U.S. Small Business Administration does not usually lend money directly. Instead, it guarantees a portion of loans made by approved banks, credit unions and other lenders, which reduces the lender’s risk and makes them more willing to finance new owners.
The 7(a) program is the most common choice for buying a business or opening a franchise. It can be used for equipment, working capital, build-out and business acquisition, with loan amounts up to $5 million. Rates and terms are set by the lender within SBA limits.
The five things lenders weigh
Every lender has its own process, but most decisions come down to the same core questions.
- Credit: your personal credit history and how you have managed debt.
- Equity injection: how much of your own cash you are putting in.
- Experience: management or industry experience relevant to the business.
- Cash flow: whether projected or historical cash flow can comfortably cover the loan payments.
- Collateral: business and sometimes personal assets that secure the loan.
Your equity injection
For startups and complete changes of ownership, lenders typically expect the buyer to contribute a meaningful share of the project cost, often around 10% and sometimes more. Lenders will ask where that money comes from, so keep clear records of savings, gifts or retirement rollovers.
What to bring to your first meeting
Showing up organized signals that you will run the business the same way.
- A business plan with realistic monthly projections for at least the first two years
- Personal financial statement and three years of personal tax returns
- A résumé that highlights management and industry experience
- For a franchise: the FDD and franchise agreement
- For an acquisition: three years of the business’s tax returns and financial statements
- A sources-and-uses table showing exactly where every dollar goes
Tips for first-time borrowers
Talk to more than one lender. Some specialize in franchises or acquisitions and know specific brands well. Check whether your franchise is listed in the SBA Franchise Directory, which can speed up review.
Be conservative in your projections. Lenders see optimistic plans every day. A plan that shows you have thought about a slow first year is more convincing than one that shows a rocket ship.
Keep reading
 Franchises
Cover Story · Franchising
Your First Franchise: What to Ask Before You Sign
The questions that separate a good fit from an expensive mistake, and how to get straight answers from franchisors and the owners already in the system.
8 min read
 For Sale
Buying a Business
Buying an Established Business, Step by Step
From the first conversation with a broker to the day you get the keys, here is how a typical small-business purchase unfolds.
7 min read
 Home-Based
Start Small
Home-Based Businesses Worth a Closer Look
Low-overhead business models that real people run from home, the licenses you will need in South Florida and how to tell them apart from the hype.
5 min read