For Sale · Buying a Business
Buying an Established Business, Step by Step
From the first conversation with a broker to the day you get the keys, here is how a typical small-business purchase unfolds.
By The Opportunity Mag Editors7 min read
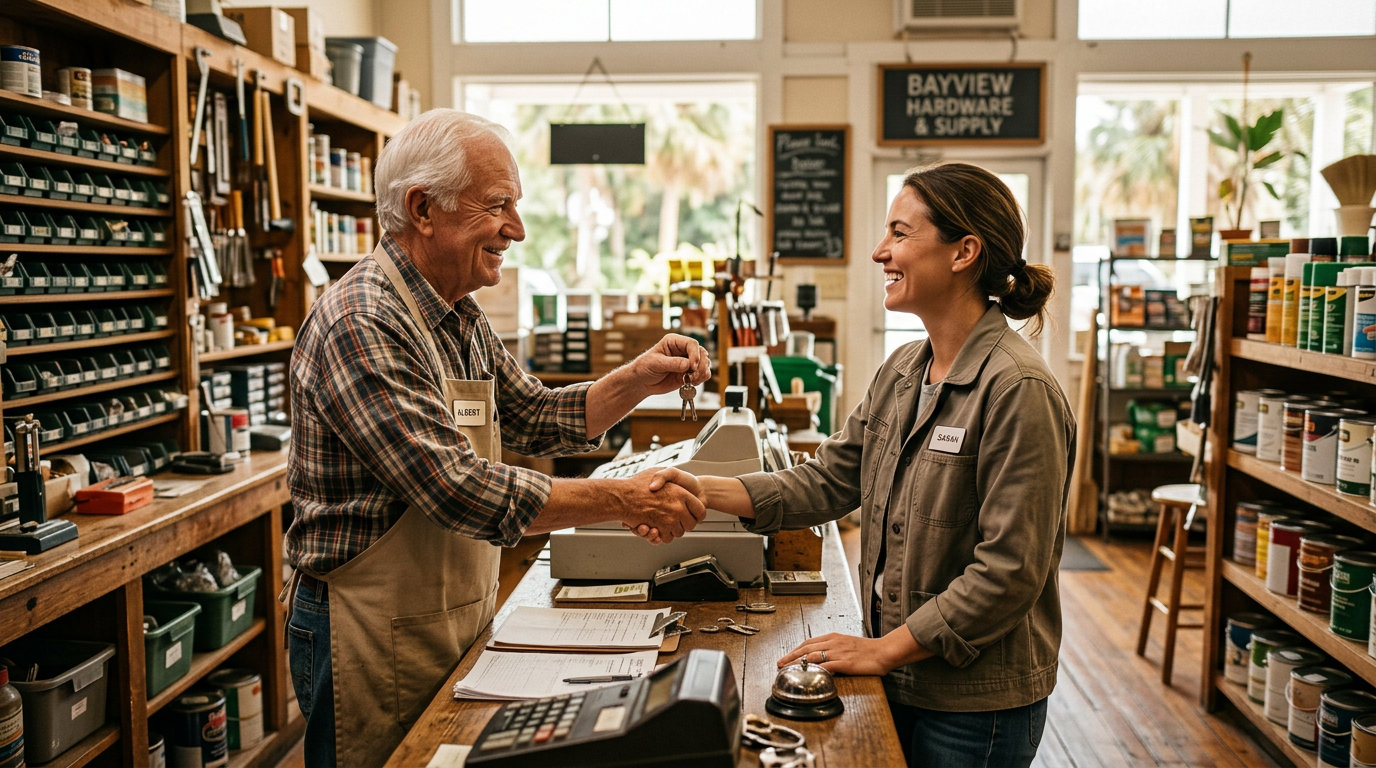
Why buy instead of start?
An established business comes with customers, staff, suppliers and a cash flow history. That can mean a faster path to income and an easier conversation with lenders. It also means you inherit whatever problems the business has. The process below is designed to surface those problems before you own them.
1. Define what you are looking for
Decide on industry, location, price range and how hands-on you want to be. Business brokers, online marketplaces and your own network are the usual sources of listings. Many sellers ask you to sign a non-disclosure agreement before sharing details.
2. Review the basics and make an offer
Once you have a confidential information package, review the seller’s financial summary, lease terms and reason for selling. If it still looks promising, you will typically submit a non-binding letter of intent (LOI) outlining the price, structure, timeline and any conditions such as financing.
3. Do your due diligence
This is where deals are won or lost. Work with a CPA and a business attorney.
- Three or more years of tax returns, profit-and-loss statements and bank statements
- Customer concentration: how much revenue depends on a handful of customers
- The lease: length, renewal options and whether it can be assigned to you
- Licenses and permits, and whether they transfer
- Employee agreements, payroll records and key staff
- Equipment condition and any liens on assets
4. Finance and close
Many small-business purchases combine buyer cash, an SBA-backed loan and sometimes seller financing. Your attorney will prepare a purchase agreement, and at closing you will sign the final documents, transfer funds and take over the business.
5. Plan the transition
Most purchase agreements include a training or transition period where the seller introduces you to customers, staff and suppliers. Treat it as part of what you are buying. A smooth handoff protects the value you just paid for.
Keep reading
 Franchises
Cover Story · Franchising
Your First Franchise: What to Ask Before You Sign
The questions that separate a good fit from an expensive mistake, and how to get straight answers from franchisors and the owners already in the system.
8 min read
 Home-Based
Start Small
Home-Based Businesses Worth a Closer Look
Low-overhead business models that real people run from home, the licenses you will need in South Florida and how to tell them apart from the hype.
5 min read
 Funding
Financing
SBA Loans Explained in Plain English
What the SBA actually does, the loan programs most new owners use and how to prepare before your first meeting with a lender.
6 min read